Does Homeowners Insurance Cover Plumbing Problems?
By the Duncan Family Plumbing team · October 5, 2026
Most homeowners policies cover sudden, accidental plumbing damage — like a burst pipe flooding a room — but not gradual problems caused by wear, neglect, or a slow leak you should have caught. Sewer and drain backups usually need a separate rider, which often costs less than $50 a year to add.
What’s Usually Covered
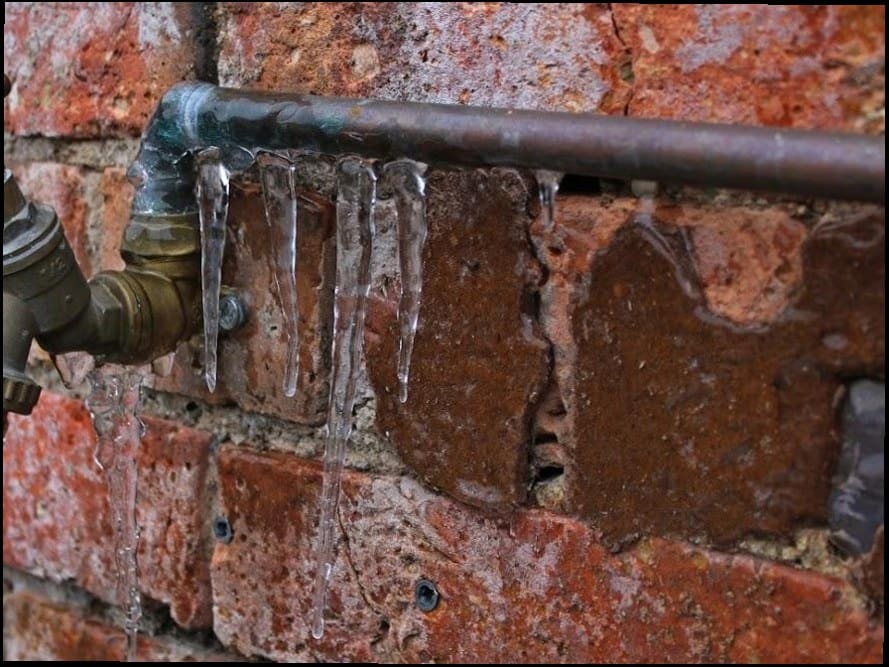
Standard homeowners policies generally cover sudden and accidental water damage — a pipe that bursts from freezing, a supply line that fails without warning, or a water heater tank that ruptures. The damage the water causes to your floors, walls, and belongings is typically covered too, along with the repair to the pipe itself in many cases.
What’s Usually Not Covered
- Gradual leaks. A slow drip that caused damage over months is often treated as a maintenance issue, not a covered loss.
- Neglect. Damage from a problem you knew about and didn’t fix.
- Sewer and drain backups. These almost always require a separate endorsement or rider — a standard policy usually excludes them.
- Flood damage. Water entering from outside, as opposed to a pipe failure inside, needs separate flood insurance.
Should You Add a Sewer Backup Rider?
If your home has an older lateral sewer line, sits low relative to the street, or you’ve had a backup before, a rider is usually worth the modest annual cost given how expensive a sewage cleanup can get.
Documenting a Claim
Photograph the damage before cleanup, keep the failed part if possible, and get a written diagnosis from a plumber explaining the cause. That paperwork makes the difference between a smooth claim and a denied one.